A letter from the Social Security Administration saying you were paid too much money can feel like a punch to the gut, especially if you’re living paycheck to paycheck or relying on that income to cover rent and groceries. The good news is that an overpayment notice is not a bill you have to pay immediately in full, and it’s not necessarily the final word. You have real options, including asking the agency to reconsider, waive, or reduce what it says you owe.
Common reasons Social Security or SSI overpayments occur
Overpayments happen more often than people expect, and in most cases they’re not caused by anything you did wrong. Social Security and Supplemental Security Income (SSI) benefits are based on information that can change from month to month, and the agency doesn’t always find out about those changes right away.
Some of the most common causes include:
A change in your income or work status that wasn’t reported or processed in time, such as starting a new job, getting a raise, or picking up more hours. For SSI recipients, an increase in household income, resources, or living arrangements (like moving in with a family member) can also affect your payment amount.
Changes in marital status, since spousal income and household size can affect SSI eligibility and payment amounts.
Medical improvement in a disability case that wasn’t reflected in your benefit right away.
Administrative errors on the agency’s end, including processing delays, miscalculations, or outdated information in the system.
Continuing to receive payments after a beneficiary has passed away, which sometimes results in an overpayment notice sent to a representative payee or family member.
In many cases, the overpayment isn’t discovered until months later, which means the amount owed can add up before anyone notices.
How you’ll be notified and what the letter usually includes
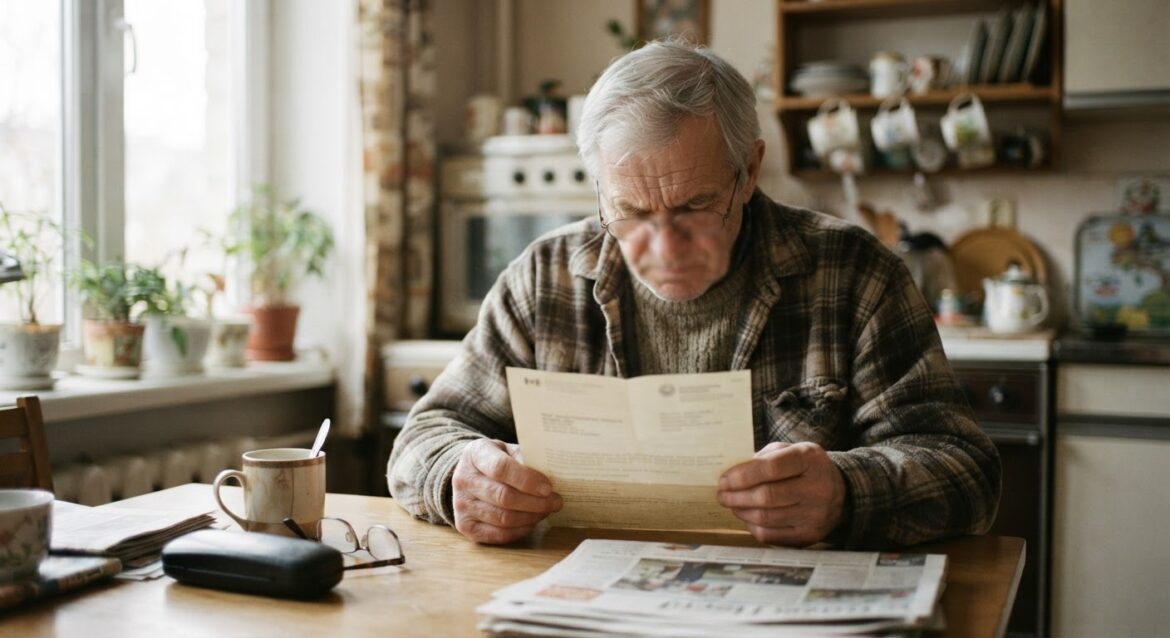
If Social Security determines you were overpaid, you’ll receive a written notice by mail. This is an important document, so it’s worth reading closely and keeping a copy for your records.
The notice typically explains why the agency believes you were overpaid, the specific time period the overpayment covers, and the total amount owed. It should also outline your rights, including the right to appeal the decision, the right to ask for a waiver, and the right to request a repayment plan instead of paying everything back at once.
You’ll usually be given a set number of days to respond before the agency starts withholding money from future benefit payments to recover the overpayment. Responding within that window matters, because it can pause collection while your request is reviewed. If you’re not sure whether a deadline has already passed, it’s worth contacting the agency directly to ask, since options may still be available even after the initial response period.
The difference between requesting reconsideration and requesting a waiver
These two options solve different problems, and it helps to understand which one fits your situation.
Requesting reconsideration means you’re saying the overpayment determination itself is wrong. Maybe the agency used incorrect income figures, miscounted your household size, or made a calculation error. If you believe you were not actually overpaid, or that the amount is wrong, reconsideration is the right path. This process involves a review of your case, and you may be able to present documents or records that support your position.
Requesting a waiver means you’re not disputing that the overpayment happened. Instead, you’re asking the agency to forgive some or all of the amount because paying it back would cause you financial hardship, and because the overpayment wasn’t your fault. Both parts typically need to be true for a waiver to be approved: the mistake wasn’t caused by something you did (like knowingly failing to report a change), and repaying it would create a genuine financial burden.
You can request a waiver even if you’re not sure the overpayment was calculated correctly, and in some cases people pursue reconsideration and a waiver at the same time. If you’re uncertain which applies to your situation, the agency’s local office can walk through the details with you before you submit paperwork.
How to set up an affordable repayment plan instead of paying in full
If you don’t dispute the overpayment and don’t qualify for a full waiver, you still don’t have to hand over the entire amount at once. Social Security allows you to request a repayment plan that fits your budget.
Typically, this involves proposing a monthly amount you can realistically afford based on your income and expenses. The agency will ask for details about your household finances to determine what’s reasonable. If you’re currently receiving benefits, repayment may happen through a reduction in your monthly payment rather than a separate bill.
It’s worth being upfront and specific about what you can afford. If a proposed repayment amount would leave you unable to cover housing, utilities, or food, you can explain that and ask for a lower monthly amount. The goal on both sides is usually to find a repayment schedule that recovers the money without pushing your household into crisis.
If your financial situation changes later, whether it improves or gets harder, you can typically reach out again to adjust the payment plan rather than sticking with an arrangement that no longer fits.
What happens if you don’t respond to the notice
Ignoring an overpayment notice doesn’t make it go away. If you don’t respond within the timeframe given, Social Security will generally begin recovering the money automatically, often by withholding all or part of your monthly benefit payment until the balance is paid off.
For people relying on that income to cover basic living expenses, a full withholding can be especially hard to absorb. This is exactly why it helps to respond as early as possible, even if you’re not sure yet whether you want to appeal, request a waiver, or set up a payment plan. Reaching out and asking for more time or clarification is almost always better than letting the deadline pass without any response.
If the recovery process has already started and it’s causing a hardship, you can still request a change to the repayment amount or ask about pausing collection while a waiver or reconsideration request is reviewed.
Where to get help if you believe the overpayment notice is wrong
If something about the notice doesn’t add up, whether the dates look wrong, the amount seems inflated, or you never received the extra money at all, you’re allowed to ask questions and push back.
Start by contacting the Social Security office handling your case, either by phone or in person, and ask for a clear explanation of how the overpayment amount was calculated. Request copies of any records or worksheets used to reach that number. You have the right to see the information behind the decision.
Local nonprofit organizations, senior centers, and legal aid clinics in many communities offer free help understanding Social Security notices and preparing appeal or waiver paperwork, particularly for older adults, people with disabilities, and low-income households. These groups can help you organize documents and understand your notice, even if they can’t guarantee a specific outcome.
Whatever you decide to do, try not to let the notice sit unanswered. Overpayment cases are common, the process for disputing or resolving them is well established, and taking the first step, whether that’s a phone call or a written request, is often the hardest part.