If you’ve ever wondered why your child’s Medicaid plan covers braces and eye exams without much fuss, but your own dental or vision coverage seems murky or nonexistent, you’re not imagining things. The rules really are different for adults, and understanding why can help you figure out what to expect from your own coverage.
Why adult dental and vision coverage is “optional” while children’s isn’t
Medicaid is a joint federal-state program, and federal law sets a baseline of services that every state must cover for enrollees under 21. That baseline, often referred to by the acronym EPSDT, requires states to provide dental care, vision screenings, and corrective lenses to children as part of routine, comprehensive checkups. There’s no getting around it — if a child is enrolled in Medicaid, dental and vision care are part of the deal.
For adults, the federal rules work differently. Dental and vision services fall into a category called “optional benefits.” States are allowed to offer them, and most do in some form, but they’re not required to, and they have wide latitude over how generous or limited that coverage is. This is the same category that includes things like physical therapy or prosthetic devices for adults — services that federal law permits but doesn’t mandate.
The practical effect is that your adult Medicaid dental and vision benefits depend heavily on which state you live in, and even on decisions your state legislature makes from one budget cycle to the next. A benefit that exists this year isn’t guaranteed to exist in exactly the same form next year.
From emergency-only extractions to full comprehensive care
Because states have so much discretion, the range of what “adult dental coverage” actually means varies enormously. At one end, some states limit adult dental benefits to emergency care only — think severe pain, infection, or trauma that typically results in an extraction rather than a restoration. If you’re in one of these states, routine cleanings or fillings likely aren’t covered at all, even though a tooth extraction in an emergency would be.
In the middle, many states offer a limited benefit package that includes some preventive and basic restorative care — for example, one cleaning and exam per year, X-rays, and fillings, but with cost caps or a limit on the number of procedures covered annually.
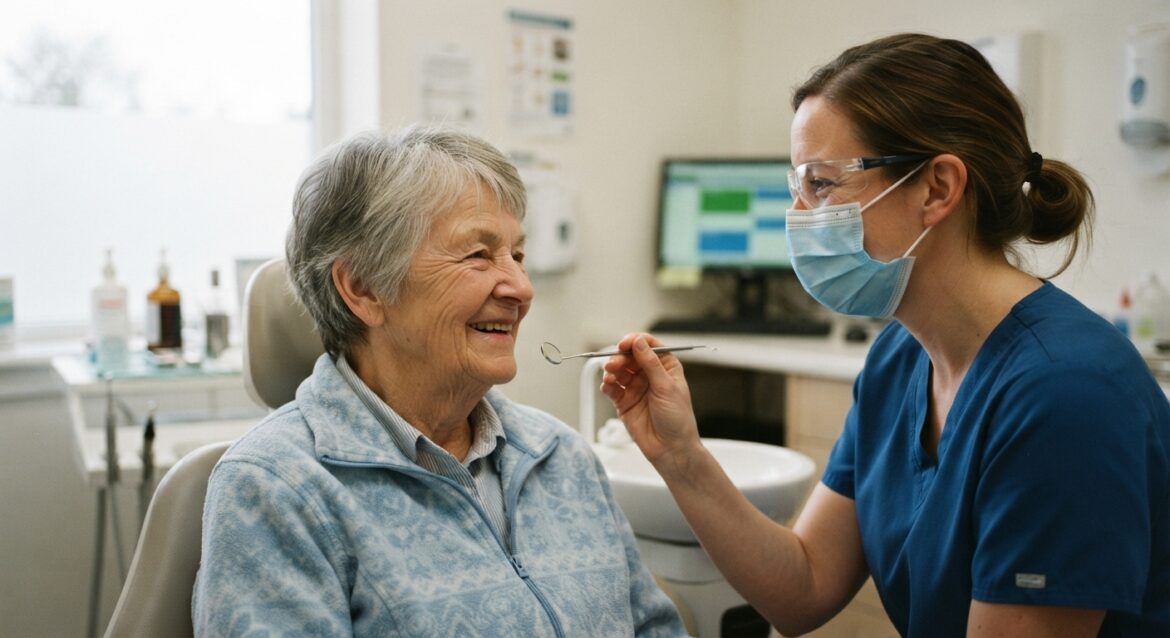
At the more generous end, a smaller number of states offer what’s typically described as comprehensive or extensive dental coverage for adults, which can include preventive visits, restorative work like fillings and crowns, periodontal treatment, dentures, and sometimes root canals.
Vision coverage tends to follow a similar pattern, though the categories are simpler: some states cover only medically necessary eye care (treating an eye disease or injury), while others also cover routine eye exams and a basic pair of glasses on a set schedule, such as once every one or two years.
What’s typically included — and where the limits usually show up
Even in states with broader benefits, coverage almost always comes with limits. It helps to know where those boundaries commonly appear:
Dental exams and cleanings: Often limited to once or twice per year. Going beyond that frequency usually means paying out of pocket, even if the visit itself would otherwise be covered.
Fillings and basic restorative work: Commonly covered, but states may limit the number of covered surfaces or teeth per year, or require prior authorization for anything beyond a simple filling.
Root canals and crowns: These are covered in some states and not others, and where they are covered, they often require documentation that a less expensive option (like an extraction) isn’t appropriate.
Dentures: Full or partial dentures are a common benefit in states with more comprehensive dental packages, but replacement dentures are usually only covered after a set number of years, and adjustments or repairs may have their own limits.
Eyeglasses: When covered, glasses are typically limited to a standard frame and lens option once every one to two years. Upgrades like designer frames, anti-glare coatting, or contact lenses in place of glasses are frequently excluded or only partially covered.
Cosmetic procedures: Across virtually every state, anything considered cosmetic — teeth whitening, cosmetic dental bonding, or non-prescription cosmetic contact lenses — is excluded from Medicaid coverage entirely.
Annual dollar caps are another common limit. Some states cap total adult dental spending per enrollee per year at a set amount, after which the enrollee is responsible for the remaining cost.
How to check what your state actually covers
Because benefit packages change and vary so much, the most reliable way to know what’s covered where you live is to go directly to the source rather than rely on general information (including this article) for specifics. A few practical steps:
Start with your state Medicaid agency’s website, sometimes listed under a different name such as a “Health and Human Services” or “Medical Assistance” department. Look for a benefits handbook or a page specifically describing adult dental and vision services.
Call the member services number on the back of your Medicaid card or in your enrollment materials. Representatives can tell you exactly what’s covered under your specific plan, including any annual limits or prior authorization requirements.
If you’re enrolled in a Medicaid managed care plan (common in many states), check with that specific plan rather than general state Medicaid information, since managed care organizations sometimes offer added benefits beyond the state’s minimum package.
Ask specifically about prior authorization. Many procedures beyond basic cleanings and exams require your provider to get approval before treatment, and finding this out after the fact can lead to unexpected bills.
Finding a provider who accepts your coverage
Having a benefit on paper doesn’t help much if you can’t find a dentist or eye doctor nearby who accepts Medicaid. Provider participation varies by region, and dental providers in particular sometimes limit how many Medicaid patients they take.
Your state Medicaid website or member services line can usually provide a provider directory or search tool. If you’re in a managed care plan, your plan’s directory is the place to start, since it may differ from the state’s general list.
Community health centers are worth checking regardless of where you live. Many operate on a sliding fee scale, accept Medicaid, and include dental services on-site or through a referral network. Some also offer vision screenings or partner with local providers for eye care. You can typically find a nearby center through a federal health center locator tool available online.
If you need care your state doesn’t cover
When a needed procedure falls outside your state’s Medicaid dental or vision benefit, you still have options, even if none of them are as simple as full coverage.
Dental schools affiliated with universities often provide care performed by supervised students at reduced rates. Treatment can take longer since it’s part of a training program, but the cost savings can be significant.
Sliding-scale clinics, including many federally supported health centers, adjust fees based on income, sometimes bringing a cleaning or extraction within reach even without insurance coverage.
Local and national vision charities occasionally run free or low-cost eye exam and eyeglasses events, particularly in underserved areas. Checking with local community organizations, libraries, or social service offices can help you find out about upcoming events in your area.
Some dental and vision providers also offer in-house payment plans for services not covered by Medicaid, allowing you to spread out the cost rather than paying all at once.
Pregnancy and temporary expanded dental benefits
If you’re pregnant and enrolled in Medicaid, it’s worth checking whether your state offers expanded dental benefits during pregnancy, even if your standard adult benefit is limited. Some states recognize the connection between oral health and pregnancy outcomes and temporarily broaden covered services — sometimes including more frequent cleanings or additional restorative care — for the duration of pregnancy and a period afterward.
This expanded coverage, where it exists, is usually tied specifically to pregnancy-related Medicaid eligibility and may end once that eligibility period closes. If you think you might qualify, your state Medicaid agency or your prenatal care provider’s office can tell you whether this applies and what documentation, if any, is needed to access it.