What the Family Self-Sufficiency Program Is and Who Runs It
If you use a Housing Choice Voucher (often called Section 8), you may have noticed a quiet catch built into the way rental assistance works: as your income goes up, your share of the rent goes up too, and your subsidy shrinks. That’s by design, but it can also feel discouraging if you’re trying to save money, pay down debt, or work toward buying a home. The Family Self-Sufficiency program, known as FSS, was created by the U.S. Department of Housing and Urban Development specifically to soften that trade-off.
FSS is a voluntary program offered through local public housing authorities, the same agencies that administer your voucher. Not every housing authority runs an FSS program, and participation is optional even where it’s offered. The basic idea is simple: instead of your increased rent payments simply reducing the amount of subsidy you receive, a portion of that increase is set aside in a savings account you can access later. In effect, the program lets you keep more of the financial benefit of a raise or a new job while you’re still receiving housing assistance.
HUD sets the overall rules and funding structure for FSS, but each local housing authority runs its own version of the program, including how many households it can enroll and how much staff support is available. Some housing authorities also offer FSS to residents of public housing, not just voucher holders, so if you live in public housing it’s worth asking whether a similar option exists for you.
How the Escrow Savings Account Grows as Your Earned Income Increases
The financial mechanics of FSS center on something called an escrow account. When you join the program, the housing authority calculates your household’s rent contribution based on your income at that time. This is your baseline. As your earned income rises during your time in the program, your rent contribution normally would rise too, and your subsidy would fall. Under FSS, though, the housing authority estimates what that increase in your rent payment would be, and instead of simply collecting it, a portion is credited to an escrow account set aside in your name.
In practical terms, this means that when you get a raise, take on more hours, or move into a higher-paying job, you don’t feel the full pinch of a shrinking subsidy right away. Part of what would have been lost is instead being saved on your behalf. Over time, as your income continues to grow, more money accumulates in the account.
It’s worth understanding that the escrow credit is based specifically on increases in earned income, such as wages from a job. Other changes in household income or circumstances may be treated differently, and housing authorities use a set formula to calculate the credit rather than crediting the full dollar amount of any raise. The exact calculation can vary somewhat by housing authority, so if you’re curious about the math for your own household, your FSS caseworker can walk you through how your particular escrow credits are being calculated.
You generally cannot withdraw funds from the escrow account while you’re actively participating in FSS and still under contract, except in certain limited circumstances that your housing authority can explain. The account is meant to build steadily in the background while you focus on your goals, rather than functioning like a regular savings account you dip into for everyday expenses.
The Five-Year Contract, Case Management, and Goal-Setting Requirements
Joining FSS means signing a Contract of Participation, which typically runs for five years, though extensions are sometimes possible under certain conditions. This contract is a two-way commitment. The housing authority agrees to set up your escrow account and provide support services. In return, you agree to work toward specific goals and, in most cases, to have at least one adult household member who is employed or actively working toward employment by the end of the contract term.
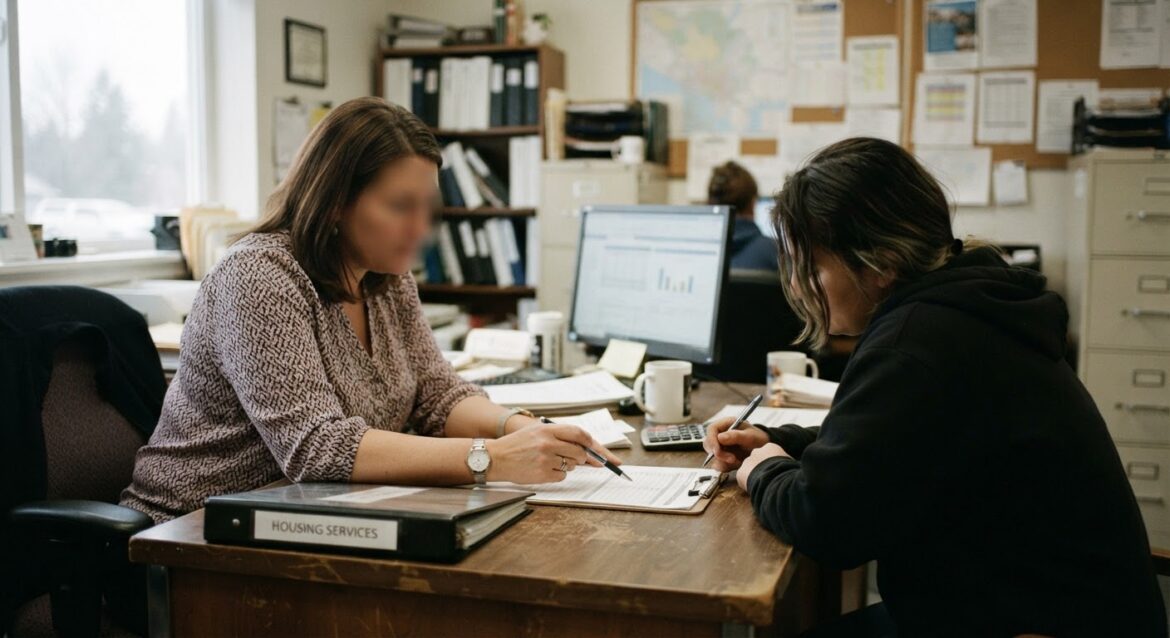
A central part of FSS is case management. When you enroll, you’ll typically work with an FSS coordinator to create an Individual Training and Services Plan. This is essentially a roadmap of goals you want to accomplish during your five years in the program. Common goals include finishing a degree or certification, completing job training, paying down debt, improving credit, saving toward a specific purchase like a car needed for work, or eventually purchasing a home. Your coordinator can also help connect you to community resources such as job placement services, childcare assistance, transportation help, financial counseling, or educational programs, depending on what’s available locally.
Throughout the contract period, you’ll likely have regular check-ins with your coordinator to track progress, adjust goals if your circumstances change, and make sure you’re on pace to meet the program’s requirements by the end of the term. This ongoing support is one of the more distinctive parts of FSS compared to simply holding a voucher on your own. It’s designed to be a partnership rather than just a savings mechanism.
How FSS Differs From Simply Earning More While on a Voucher
Without FSS, the general rule for voucher holders is straightforward: your portion of the rent is tied to your income, so as income rises, your rent share rises and your subsidy falls. There’s no separate savings mechanism built into the standard voucher structure. Some households find this discouraging, since a raise or a second job doesn’t always translate into as much financial breathing room as they’d hoped, at least not immediately, because more of the household budget is going toward rent.
FSS changes that dynamic in two main ways. First, it creates the escrow account described earlier, so a portion of what would have gone toward increased rent is instead saved for you. Second, it wraps that financial incentive in a structured support system, complete with a coordinator, a written goal plan, and access to referrals for training, education, or other services. In other words, FSS isn’t just a different rent formula. It’s a program designed to help you build both income and savings over a defined period, with someone checking in along the way.
This structure also means FSS involves more commitment than simply staying on a voucher without enrolling in any special program. You’re agreeing to work toward goals and meet with a coordinator regularly, and there are employment expectations tied to the contract. For some households, this added structure is exactly the accountability and support they’re looking for. For others, especially those who prefer not to have additional program requirements, staying on a standard voucher without FSS may make more sense. It’s a personal decision, and your local coordinator can help you think through what fits your situation.
What Happens to the Escrow Funds When You Complete or Leave the Program
If you complete your FSS contract successfully, meaning you’ve met the goals in your plan and satisfied the employment requirement, the funds in your escrow account typically become available to you. Many housing authorities allow you to use these funds for any purpose at that point, whether that’s paying off debt, covering education costs, building a larger savings cushion, or working toward homeownership. Because the account may have been growing for years, depending on how much your income increased during the contract, the payout can represent a meaningful sum for many households.
If you leave the program early, lose your voucher, or don’t complete the requirements by the end of the contract term, the outcome for your escrow funds can vary. In some cases, you may be able to receive a portion of the funds, particularly if you’ve made genuine progress toward your goals. In other cases, funds that haven’t yet been earned under the program’s rules may not be available to you. Because these rules differ by housing authority and depend on your specific circumstances, it’s important to ask your FSS coordinator directly what would happen to your escrow balance under different scenarios, ideally before you sign the contract, so you know what to expect.
It’s also worth knowing that housing authorities are generally required to review your escrow balance periodically and let you know how much has accumulated, so you’re not left guessing. If you haven’t received an update in a while, it’s reasonable to ask your coordinator for a current statement.
How to Find Out if Your Local Public Housing Authority Offers FSS
Because FSS is administered locally, the first step is contacting the public housing authority that issued your voucher. You can typically find contact information on the paperwork you received when your voucher was approved, or by searching for your housing authority’s name along with “Family Self-Sufficiency program” to see if they publish information online. When you reach out, ask specifically whether they have an active FSS program, whether there’s a waiting list, and what the enrollment process looks like.
If your local housing authority doesn’t currently offer FSS, or has a waiting list, it may still be worth asking what other savings or self-sufficiency supports they have available, since some agencies offer similar initiatives under different names or through partnerships with local nonprofits. Even if FSS isn’t accessible right now, understanding the landscape of what’s offered locally can help you plan your next steps.
For households who do have access to FSS, taking time to ask detailed questions before enrolling, about how the escrow formula works, what the employment requirement really means for your situation, and what support services are included, can help you decide whether the program’s structure fits your goals. It’s a program built around the idea that gaining stability shouldn’t mean losing ground financially, and for many voucher holders, that combination of savings and support has made a real difference over the years.